Pay Off the Mortgage Early or Invest? A Plain Comparison
One option buys certainty, the other buys growth potential. Here is how the two compare, and the questions that usually decide it.
 03 / Retirement money · Comparison
In this story 4 sections
Sometime in your forties, if you are lucky, there is a bit of money left at the end of the month. And with it comes one of the great dinner-party arguments: do you throw it at the mortgage or put it into investments? One camp says being debt-free is priceless. The other says you are wasting decades of potential growth. Both camps are usually very confident, and both are sometimes right.
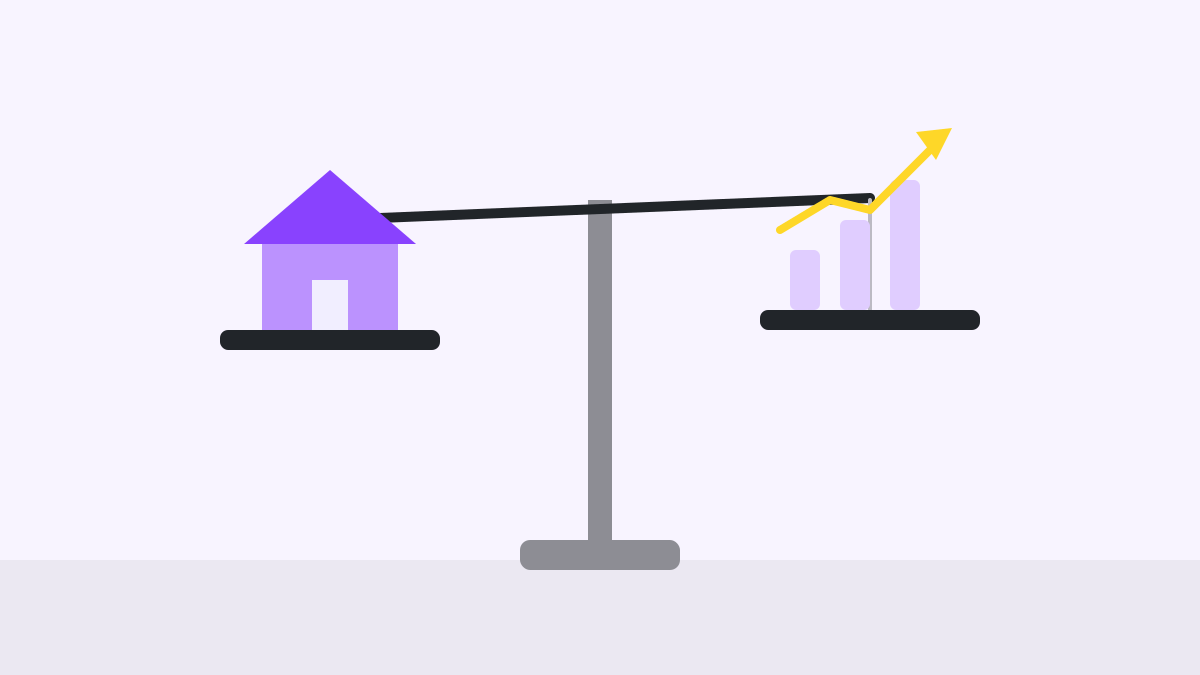
I have flip-flopped on this myself more than once. What finally helped was setting aside the question of which option is better in general and asking which one suits our household right now. Here is how the two stack up, side by side.
Before you choose either
There is an order of operations that most general guidance agrees on, and it comes before this decision. If any of these are not in place, they usually deserve your spare money first:
- An emergency fund. Enough cash to cover a few months of essential costs. Money in your house or in investments is not much help when the car dies this week.
- Expensive debt cleared. Credit cards and other high-interest borrowing almost always cost more than a mortgage, so they are the first thing to overpay.
- Your full employer match. If your workplace pension or retirement plan matches your contributions, getting the full match is hard to beat with either option.
The two options compared
At heart, overpaying a mortgage is a guaranteed, risk-free return equal to your interest rate, because every amount you pay off is an amount you no longer pay interest on. Investing offers the possibility of a higher return over the long term, but with ups and downs along the way and no promise of any particular outcome.
| Factor | Overpay the mortgage | Invest the money |
|---|---|---|
| Return | Guaranteed: the interest you avoid paying | Variable: could be higher or lower, with no guarantee |
| Risk | Very low, though your money is tied up in your home | Values can fall, especially over short periods |
| Access to the money | Usually hard to get back without remortgaging or selling | Often accessible, though pensions and some accounts lock money away |
| Tax treatment | No tax to pay on interest saved | Depends on the account and where you live |
| Peace of mind | High for many people, especially near retirement | Depends on your comfort with market swings |
The interest rate does a lot of the work here. The higher your mortgage rate, the more attractive a guaranteed saving becomes. When rates are low, investing has historically had more room to come out ahead over long periods, though past performance does not guarantee anything about the future.
Questions that usually decide it
How long until you need the money? Investments generally need time to ride out bad years. If you are thinking in terms of a few years, the guaranteed saving looks more appealing. If you are thinking in decades, investing has more time to work.
How would you feel in a bad year? Be honest. If a sharp fall in your investments would keep you up at night, or tempt you to sell at the worst moment, the steadier option may serve you better even if it might earn less on paper.
What does your mortgage allow? Many mortgages limit how much you can overpay without charges, particularly during a fixed-rate period. Check your terms before you start, and check whether overpayments reduce your monthly payment or the length of the loan.
When do you want to be mortgage-free? Going into retirement without housing costs makes your retirement income stretch much further. For some households, that target alone tips the balance.
Why not do both?
In real life, plenty of people split the difference: a regular overpayment on the mortgage and a regular contribution to investments or a pension. It is less satisfying as an argument, but it hedges your bets. If rates rise, you have reduced your debt. If markets do well, you have some exposure. Either way, you are making progress.
Whatever you choose, review it every year or so, and again whenever your mortgage deal ends. A choice that made sense on one interest rate might look quite different on the next.
Get personal advice for big moves
This is general information, not financial advice. The right answer depends on your mortgage terms, tax position, pension arrangements and attitude to risk. A qualified, regulated financial adviser can model your numbers before you commit to either approach.
Is paying off the mortgage early always a good idea?
Are there penalties for overpaying a mortgage?
Should I use a lump sum to pay off the mortgage?
Some links may be sponsored. Our editors choose what we cover, and nothing here is financial, legal or benefits advice. Our editorial policy.
In this story 4 sections
Keep reading
- 03 / Retirement money · How-to Set Your 2027 401(k) Contribution in Your 40s 7 min read
- 03 / Retirement money · Explainer What Happens to Your Pension When You Change Careers 4 min read
- 03 / Retirement money · Explainer "Behind" on Retirement at 45? What That Actually Means, and What Still Works 5 min read